Sequence Planning Approaches for Capital Deployment in Successive Weekend and Midweek Markets
Written by Taylor Brooks · Jun 5, 2026
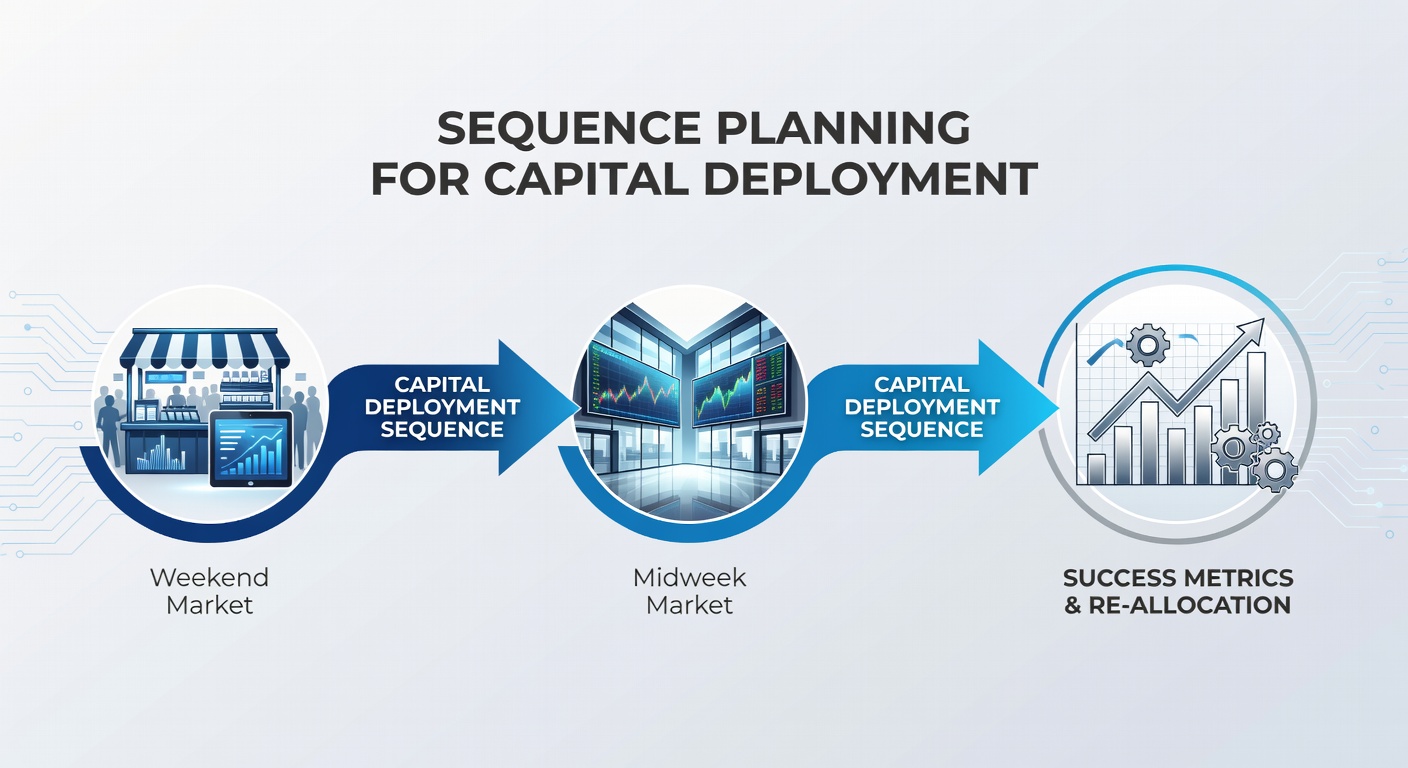
Sequence Planning Approaches for Capital Deployment in Successive Weekend and Midweek Markets
Markets that operate across weekend and midweek sessions present distinct cycles for capital deployment, and sequence planning organizes these deployments into ordered steps that align with session timings. Observers note that participants often allocate portions of available capital according to the opening and closing patterns of each session, which creates opportunities to adjust positions before the next cycle begins. Research from financial timing studies shows that such sequencing reduces overlap between high-volatility periods and allows for measured reallocation once initial results from one session become available.
Core Elements of Sequence Planning
Sequence planning begins with identifying the full cycle that stretches from Friday evening through Monday morning, then continues into Tuesday and Wednesday sessions, and researchers have documented how capital moves in stages rather than all at once. Data indicates that breaking deployment into three or four sequential tranches lets participants respond to price or odds movements that develop overnight, while a single large allocation at the start of the weekend leaves less room for mid-cycle corrections. Those who have examined trading logs across multiple seasons report that the second and third tranches frequently receive smaller portions because earlier movements supply updated information on momentum.
Timing within each tranche matters as well. Capital scheduled for weekend deployment typically targets the first hours after markets open on Saturday, whereas midweek sequences shift focus to sessions that begin later in the evening on Tuesdays. According to records compiled by market analysis firms, this staggered approach aligns with documented patterns where liquidity builds gradually rather than instantly at the session start.
Weekend Market Deployment Phases
Weekend sequences usually open with an initial assessment conducted on Friday afternoon that sets the size of the first tranche. Participants then monitor early-session activity through Saturday and Sunday, which provides data points for deciding whether the second tranche should increase, decrease, or remain unchanged. Evidence from longitudinal market reviews reveals that adjustments made between Saturday and Sunday sessions frequently reflect changes in participant volume that only become visible after the first few hours of trading.
Because weekend sessions often span longer continuous hours than midweek ones, planners incorporate rest periods into the sequence so that capital remains available for later decisions rather than being fully committed early. One analysis of deployment records across successive weekends found that sequences allowing for at least one reassessment point between day-one and day-two activity showed more consistent alignment with final cycle outcomes.
Midweek Adjustments and Reallocation
Midweek markets operate on shorter daily windows, which compresses the time available for each tranche in the sequence. Planners therefore schedule the first midweek deployment for the opening hours of Tuesday sessions, then reserve later tranches for Wednesday or Thursday based on results observed from the prior day. Figures compiled by academic researchers indicate that sequences spanning both weekend and midweek benefit when the midweek portion receives a smaller overall share, since weekend activity has already absorbed a larger slice of total capital.
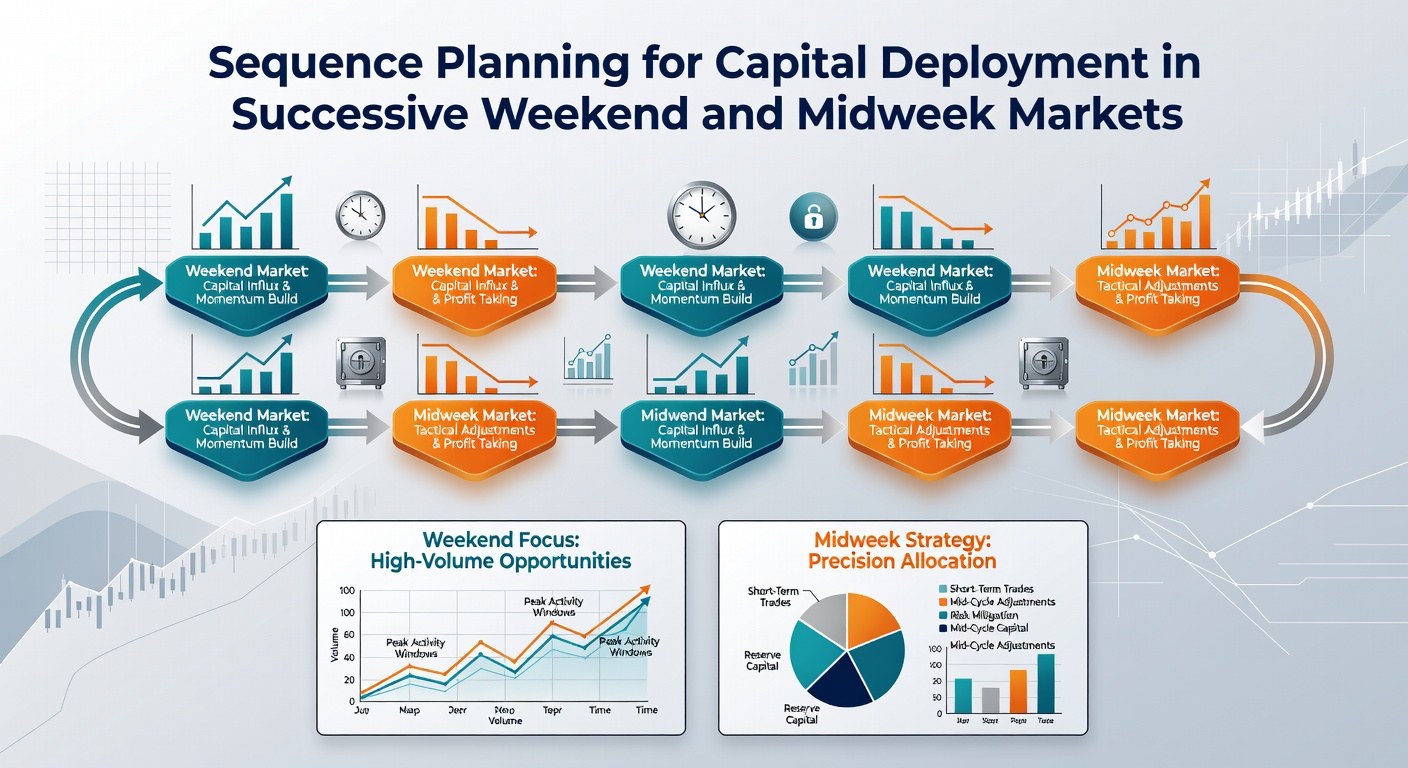
Reallocation between the weekend close and the first midweek session occurs through defined checkpoints. Those checkpoints draw on updated session data to confirm whether earlier tranches performed as projected, and any shortfall or surplus informs the size of the remaining allocations. Reports issued by international market research groups in June 2026 documented that participants following checkpoint-based sequences completed more cycles without exhausting reserves before the final session closed.
Integration of External Data Sources
Sequence planners incorporate external indicators such as volume reports and session-start liquidity measures when determining tranche sizes. Government statistical releases from agencies in Australia and Canada supply aggregated figures on market participation that help calibrate expectations for both weekend and midweek volumes. Academic studies published by European research centers further supply models that convert historical session data into projected allocation ranges, allowing sequences to be tested against multiple scenarios before capital is released.
Links to such resources appear naturally during planning meetings, for instance when referencing the latest Gambling Research Australia participation surveys or reviewing models from North American university finance departments. These inputs feed directly into the sequence rather than remaining separate from deployment decisions.
Practical Sequence Structures Observed in 2026
Records from the first half of 2026 illustrate sequences that placed 40 percent of available capital in the initial weekend tranche, followed by 30 percent after the first reassessment and the final 30 percent distributed across midweek sessions. The structure allowed for a pause between Sunday close and Tuesday open, during which updated indicators could be reviewed without pressure to act immediately. Market participants following this pattern reported fewer instances of capital remaining idle across an entire cycle, according to aggregated transaction summaries released by industry monitoring organizations.
Alternative sequences observed in the same period shifted more capital toward midweek tranches when weekend volumes appeared lighter than historical averages. Such adjustments relied on the same checkpoint system, yet altered the percentage split once early data arrived. The flexibility built into the sequence prevented rigid adherence to percentages that no longer matched observed conditions.
Conclusion
Sequence planning for capital deployment across successive weekend and midweek markets organizes allocations into ordered tranches that respond to session-specific timing and data updates. Records and research summaries show that checkpoint-based structures, combined with external volume indicators, produce measurable alignment between planned and executed deployments. Continued observation of these patterns supplies the factual basis for refining sequences in future cycles.