Charting Allocation Thresholds: Aligning Variance Models With Seasonal Cycle Data for Layered Wager Structures
Written by Ulrich Peters · Aug 23, 2026
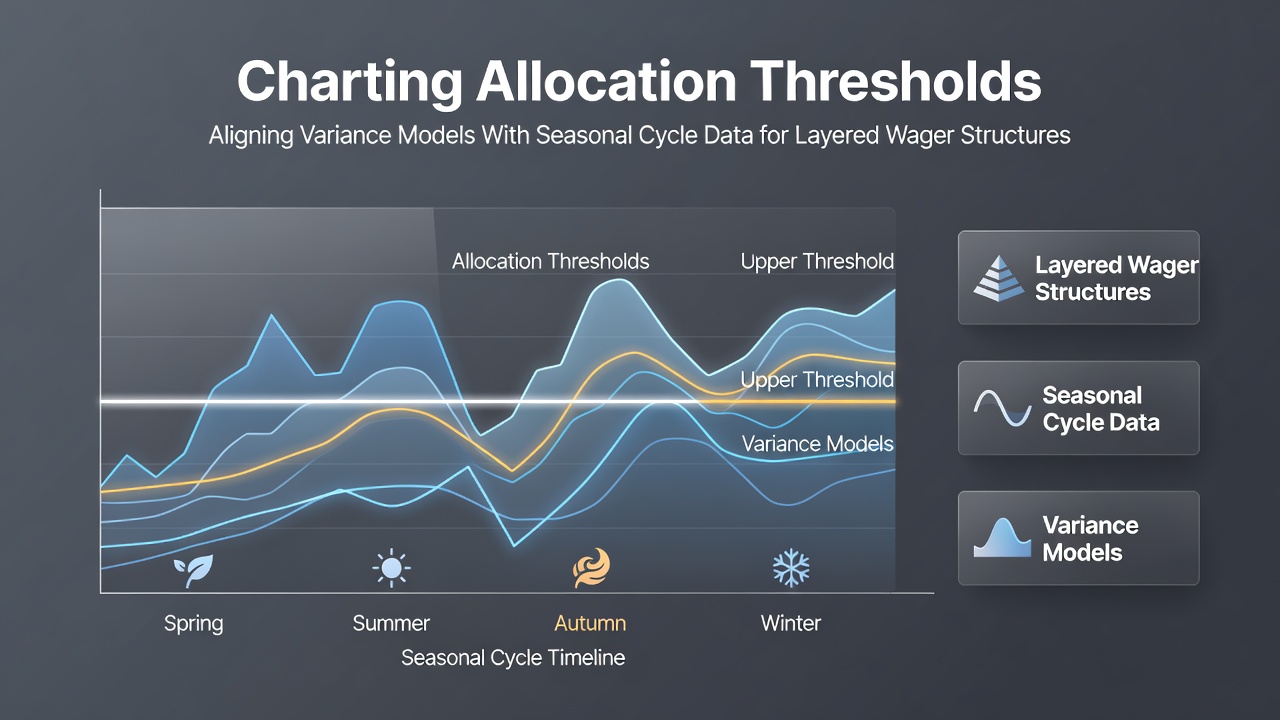
Charting Allocation Thresholds: Aligning Variance Models With Seasonal Cycle Data for Layered Wager Structures
Statistical frameworks for wager allocation rely on variance models that quantify outcome dispersion across repeated events, and these models gain precision when integrated with seasonal cycle data that captures recurring fluctuations in participation rates and outcome distributions throughout the year. Researchers in quantitative analysis have examined how periodic shifts in event frequency, such as those observed in major sports leagues during August 2026, influence the stability of allocation thresholds that determine when capital moves between different wager layers.
Core Elements of Variance Modeling
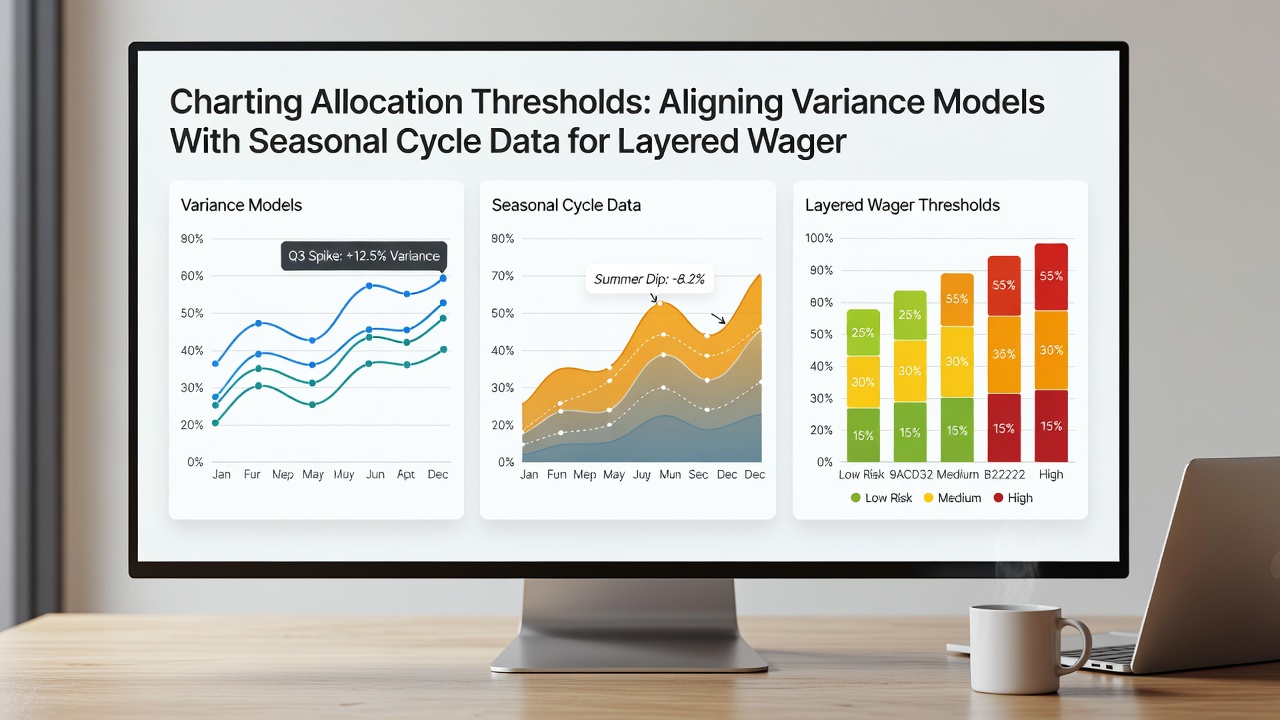
Variance models calculate the expected spread of results by applying formulas that incorporate historical performance metrics, probability distributions, and covariance terms between related events, while seasonal cycle data supplies adjustments for periods of heightened activity or reduced volume that alter those distributions. Data from industry reports indicate that allocation thresholds often shift by measurable percentages when cycle peaks coincide with tournament schedules, creating opportunities for recalibration that maintain risk parameters within defined bounds. Observers note that layered wager structures divide total exposure into segments with distinct variance tolerances, allowing higher-variance positions in one layer to offset lower-variance positions in another without breaching overall portfolio limits.
Integration of Seasonal Patterns
Seasonal cycle integration begins with decomposition of time-series data into trend, seasonal, and residual components, after which variance estimates receive multiplicative or additive corrections based on cycle phase. Studies from academic institutions demonstrate that models incorporating these corrections produce threshold recommendations that reduce drawdown frequency during transition months between high-volume and low-volume periods. In August 2026, for instance, preliminary figures from multiple sports markets showed elevated transaction volumes that aligned with predicted seasonal spikes, prompting analysts to update variance inputs accordingly before finalizing allocation rules.
Threshold Calculation Approaches
Thresholds emerge from optimization routines that solve for capital allocation percentages subject to constraints on maximum acceptable variance per layer, and these routines frequently employ Monte Carlo simulations seeded with seasonally adjusted parameters to test robustness across thousands of outcome scenarios. Evidence from research papers published by university statistics departments shows that thresholds derived this way maintain stability even when input data contain moderate levels of noise from irregular event outcomes. Layered structures further benefit when each layer receives its own variance ceiling calibrated to the cycle phase, so that aggressive allocations remain confined to layers designed for elevated dispersion.
What's interesting is how the alignment process connects historical cycle records with forward-looking variance projections, creating a feedback loop where realized outcomes from one season refine the model parameters applied to the next. Government statistical agencies in several regions publish aggregate transaction and participation datasets that supply the raw material for these refinements, enabling independent verification of seasonal effects without reliance on proprietary operator data.
Practical Implementation in Layered Frameworks
Implementation proceeds through iterative calibration where initial thresholds derived from baseline variance estimates receive scaling factors drawn from seasonal indices, after which back-testing against prior cycles validates the adjustments. Industry organizations such as the National Council on Problem Gambling have compiled resources on responsible allocation practices that emphasize the importance of transparent threshold documentation, while research from Canadian institutions highlights how cycle-aware models can inform operator reporting requirements in regulated markets. Allocation decisions then follow predefined rules that move capital only when projected variance at the current cycle phase falls within the layer-specific band.
Those who've examined multi-year datasets observe that misalignment between variance assumptions and seasonal realities tends to concentrate during shoulder periods between major cycles, where small errors in cycle phasing amplify threshold deviations. Corrective procedures involve re-estimating seasonal factors using rolling windows of recent observations, a technique that several quantitative teams have adopted to keep allocation bands current. External validation comes from cross-referencing with Australian Gambling Research Centre publications that track comparable seasonal patterns in wagering activity across different jurisdictions.
Conclusion
Charting allocation thresholds through the alignment of variance models and seasonal cycle data provides a structured method for managing layered wager structures under varying market conditions. The approach relies on documented statistical techniques, publicly available cycle indicators, and iterative validation steps that together support consistent application across different time horizons. Continued refinement of these methods depends on access to granular seasonal datasets and ongoing collaboration between model developers and data providers in multiple regulatory environments.